UBS: Western Digital Beat and Raise, but Market Expectations Are Too Rosy
Summaries are public. PDF access requires an active membership; all members have the same access. Sign in
UBS notes that Western Digital delivered a strong quarterly performance, beating market expectations on both revenue and earnings per share, primarily driven by robust cloud storage demand. The company subsequently raised its forward revenue guidance. However, UBS cautions that the market reaction has been overly optimistic, with the stock price largely pricing in these short-term positives. The bank highlights that the magnitude of the guidance raise fell short of what some bullish investors had anticipated.
Underlying industry headwinds persist and remain unresolved. The hard disk drive (HDD) business continues to face long-term competitive pressure from solid-state drives (SSDs), threatening market share. Furthermore, NAND flash price volatility remains a significant source of earnings uncertainty. Although artificial intelligence related storage demand provides a long-term tailwind, its near-term financial contribution is limited. Elevated industry inventory levels suggest demand recovery could be slower than expected.
UBS maintains a Neutral rating on Western Digital with an unchanged price target of $80 per share. This valuation corresponds to roughly 12 times forward earnings for 2026. With the current stock price already approaching this target, UBS sees limited upside potential. The bank emphasizes that capital expenditure will remain elevated, constraining free cash flow improvements. Investors are advised to monitor subsequent quarterly performance, NAND pricing trends, and HDD market share dynamics.
Key exhibits
Exhibit 1
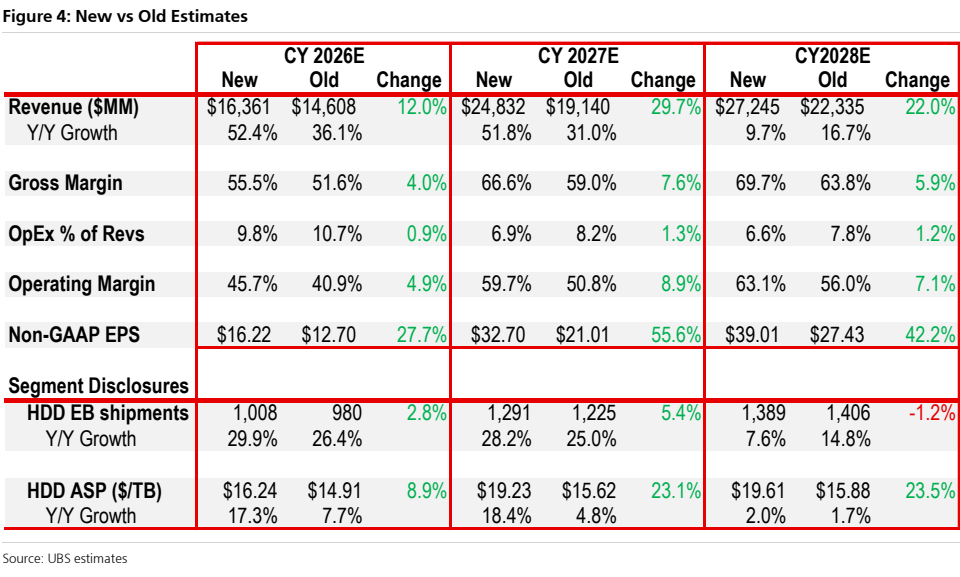
Exhibit 2

Exhibit 3

Exhibit 4
Exhibit 5

Exhibit 6

Exhibit 7

Exhibit 8
