Goldman Sachs on China Resources Beer (0291.HK): 1H26 Review — Premiumization, Operational Resilience and Outperformance Undervalued by the Market
Summaries are public. PDF access requires an active membership; all members have the same access. Sign in
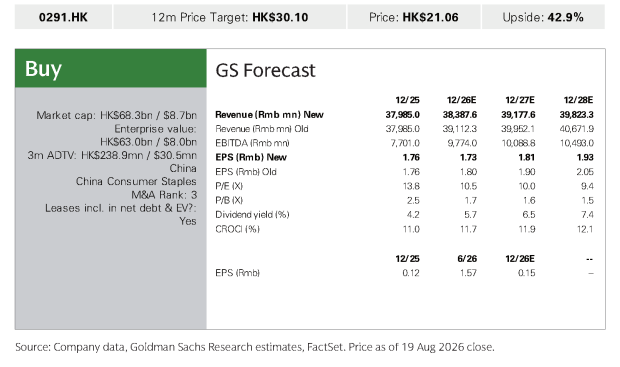
China Resources Beer's 1H26 results, published August 19, were in line, yet the stock fell 5%, a pullback Goldman Sachs views as an overreaction. Despite greater exposure to mid-to-low-end products, the industry's highest aluminum-can share (44-45%) and aluminum accounting for roughly 25% of 1H26 cost of sales, CR Beer still delivered positive volume and price-per-ton growth with broadly stable core operating profit, outperforming the industry. For 2H26, Goldman expects continued revenue outperformance on healthy momentum for Heineken, Amstel (up 80% YoY in 1H26) and Laoxue (up over 40%), an easier pricing base, healthy channel inventory and expected 4Q aluminum cost relief. The long-term premiumization target is 30-35% of volume from super-premium and above beers (26% in 1H26; 25% in 2025), while the baijiu business remains pressured in 2H26. Goldman trimmed 2026-28E sales by about 2% and recurring net profit by 4-6%, to a 2026E RMB5.6bn (-2.1% YoY), and cut its target from HK$35.15 to HK$30.1 (15.0x 2027E P/E) while maintaining Buy. At HK$21.06, upside is 42.9%, with 10.5x/10.0x 2026/27E P/E, 5.7%/6.5% dividend yields and a 10%+ FCF yield; the 2026 payout should exceed 55%, with a 60-70% future target.
Key exhibits
Exhibit 1
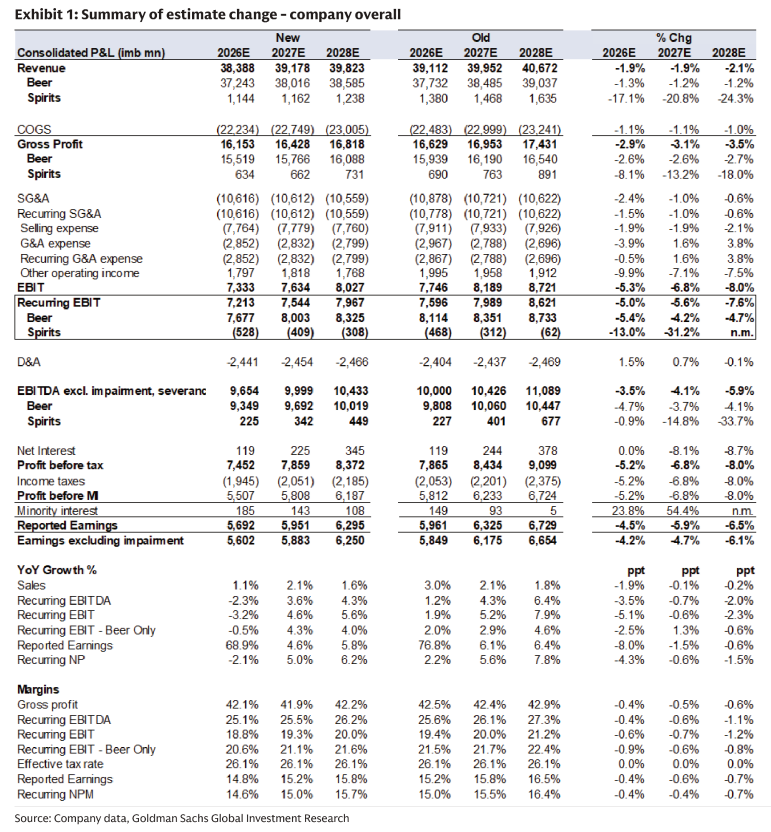
Exhibit 2
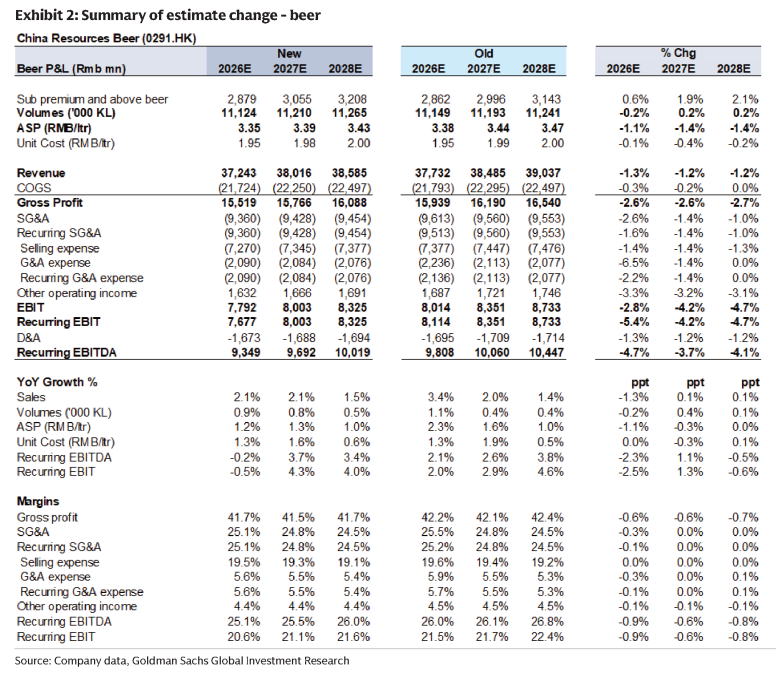
Exhibit 3