Shein (0625.HK): Attractive Valuation Against a Challenging Backdrop; 2027E Recovery Expected; Initiated at Buy
Summaries are public. PDF access requires an active membership; all members have the same access. Sign in
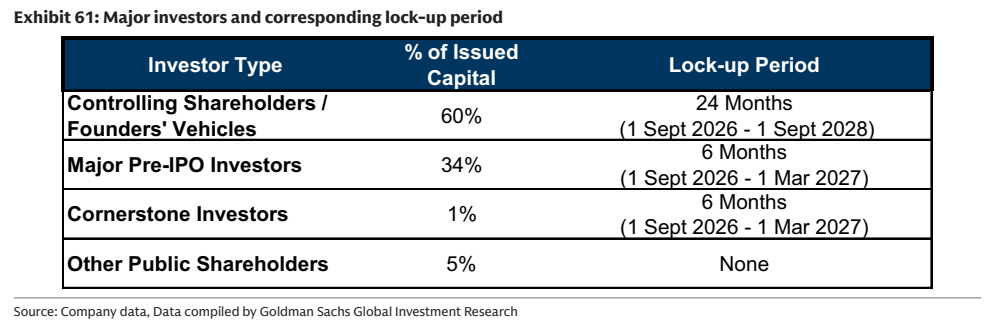
Goldman Sachs initiates coverage of Shein (0625.HK) with a Buy rating, arguing the valuation is highly attractive against a challenging operating backdrop, with a recovery expected in 2027E. The report's exhibits frame the investment case around unit economics and external headwinds: the trend in cost per order and margins, air freight rates from China to global destinations, the evolution of US and EU tariff and customs policies, and how price pass-through changes Shein's unit economics. Competitive positioning is assessed through A&F's market share in Europe, gross margin comparisons against apparel, e-commerce and retail peers, and a table of comparable company financials. On the demand side, the analysis covers online penetration of the global fashion market and compares Shein's US GMV with Temu's, noting that Bloomberg data are broadly consistent with company disclosures. Ownership structure is also reviewed, including major investors and their respective lock-up periods. Taken together, the materials map the near-term cost and policy pressures on Shein's business against the structural drivers of online fashion demand that underpin expectations of a 2027E recovery.
Key exhibits
Exhibit 1
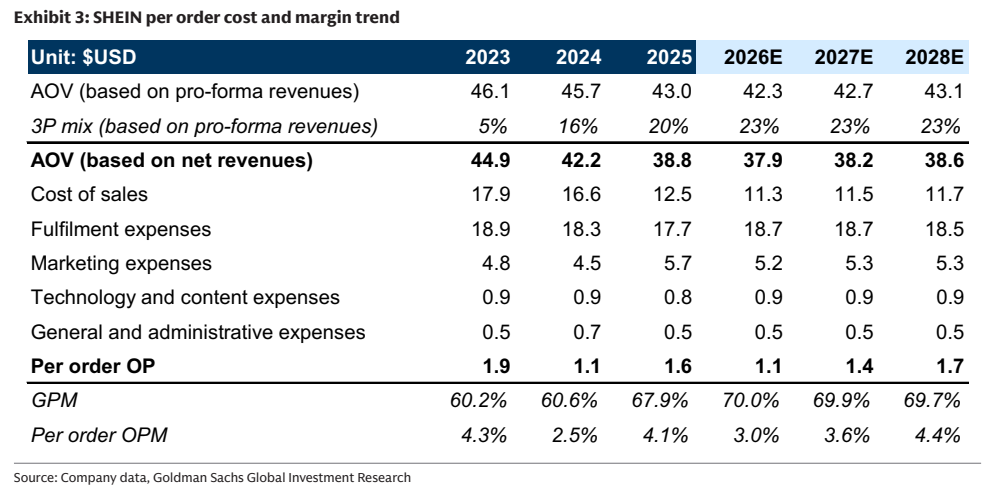
Exhibit 2
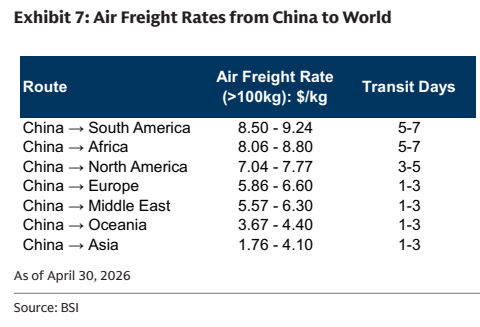
Exhibit 3
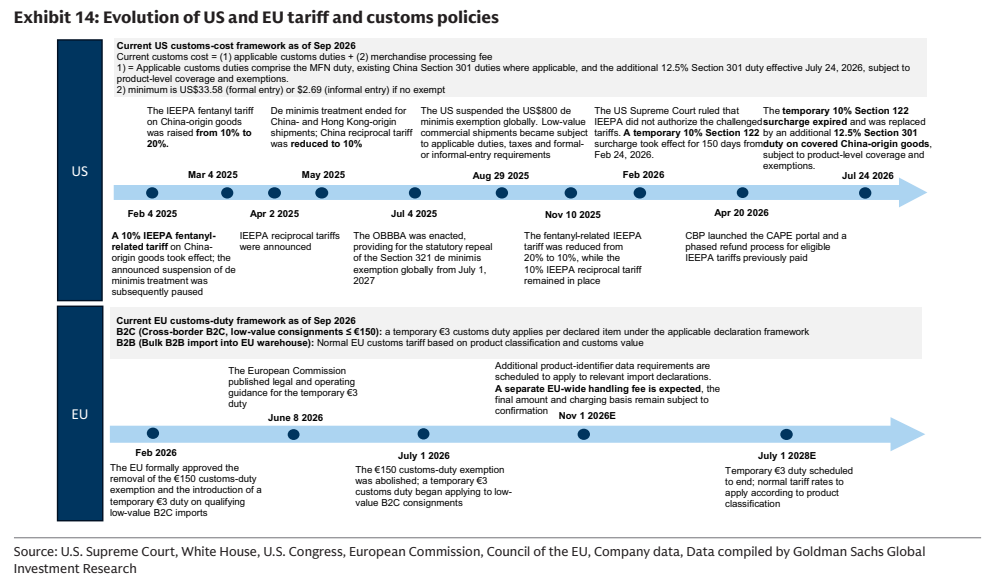
Exhibit 4
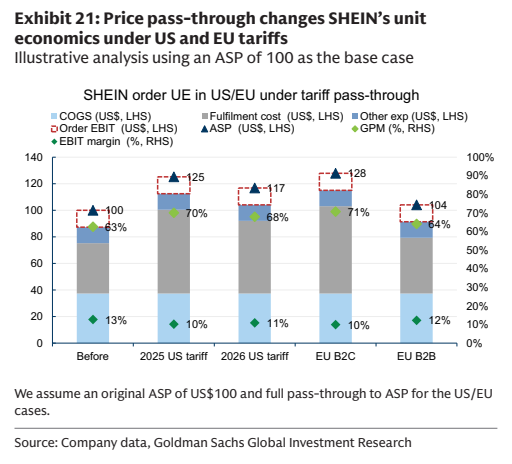
Exhibit 5
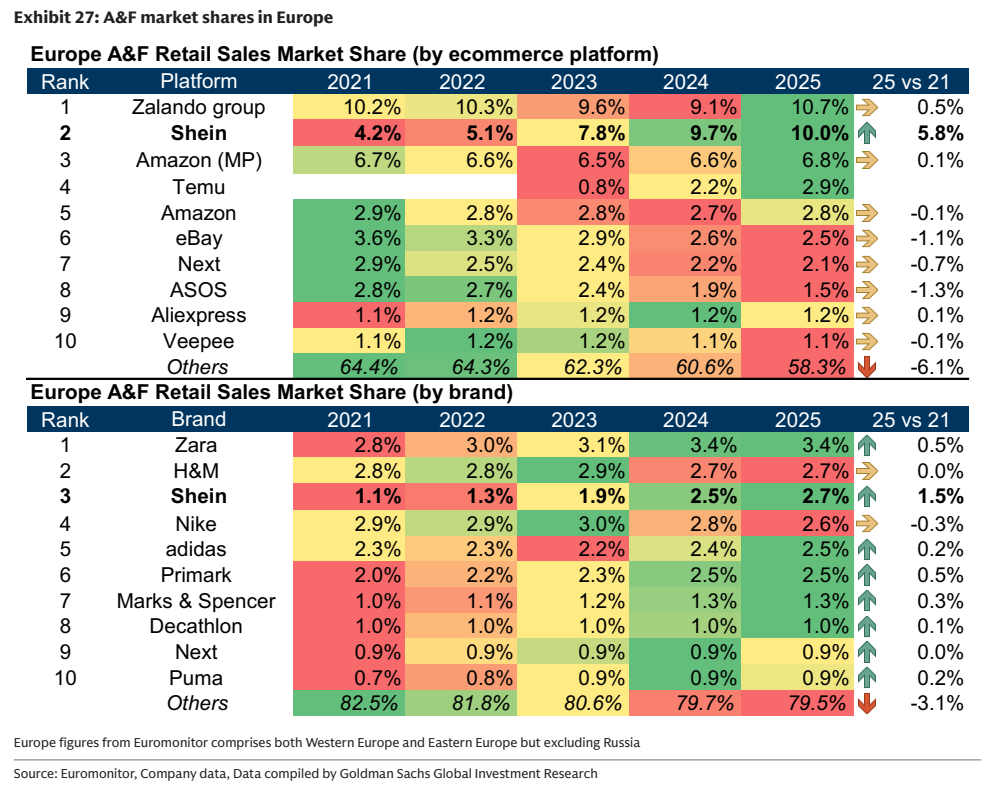
Exhibit 6
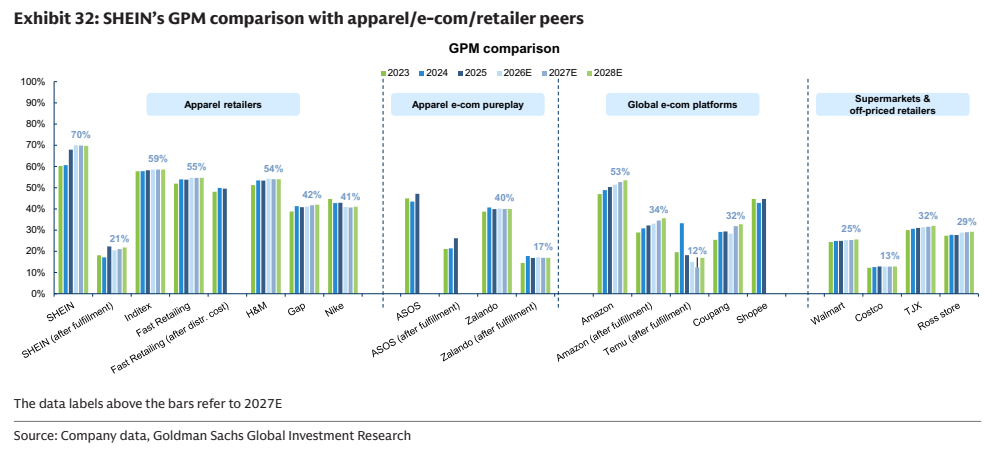
Exhibit 7
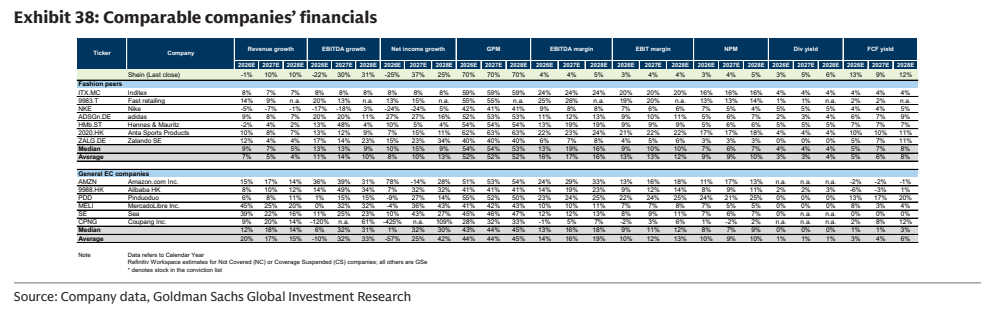
Exhibit 8
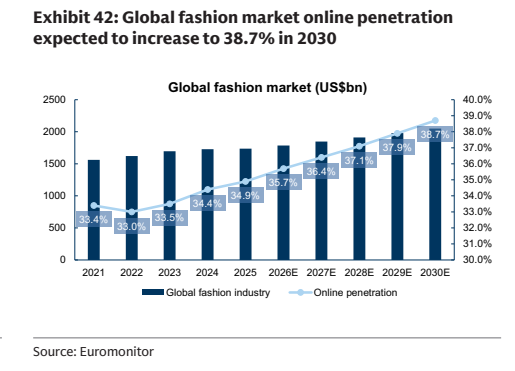
Exhibit 9
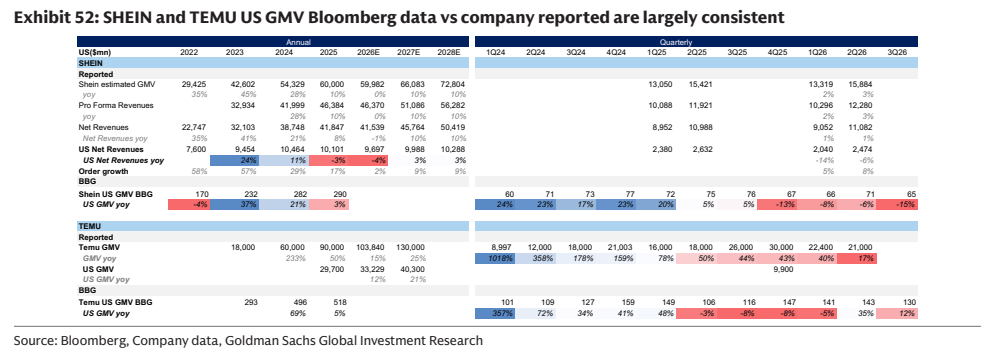
Exhibit 10