JPMorgan RMB Exchange Rate Outlook: Short-Term Pressure, Medium-Term Hinges on Policy
Summaries are public. PDF access requires an active membership; all members have the same access. Sign in
JPMorgan notes that the Renminbi faces distinct short-term depreciation pressure, driven primarily by widening yield differentials, capital outflows, and moderating export growth. The spread between 10-year Chinese and US government bonds has expanded to 150 basis points, encouraging arbitrage outflows. Furthermore, April 2026 export growth decelerated to 3.2% year-over-year, falling below consensus estimates of 5.0% and narrowing the trade surplus.
The People's Bank of China has attempted to stabilize expectations via daily fixing rates and offshore bill issuances, though the effectiveness of these measures remains constrained. With the US Dollar Index fluctuating between 104 and 106 amid sustained high interest rates, external pressure persists. However, a potential 50-basis-point reserve requirement ratio cut by the PBOC in the second half could enhance exchange rate flexibility.
Looking forward, JPMorgan projects USD/CNY will reach 7.3 by the end of the third quarter of 2026, before retracing to 7.1 by the fourth quarter. In a risk scenario characterized by deteriorating US-China relations, the currency could weaken to 7.5. Conversely, if Sino-American trade negotiations yield a phased agreement, the Renminbi may rebound below 7.0. The baseline view remains a controlled depreciation, fundamentally contingent upon central bank policy and geopolitical developments.
Key exhibits
Exhibit 1

Exhibit 2
Exhibit 3
Exhibit 4

Exhibit 5
Exhibit 6
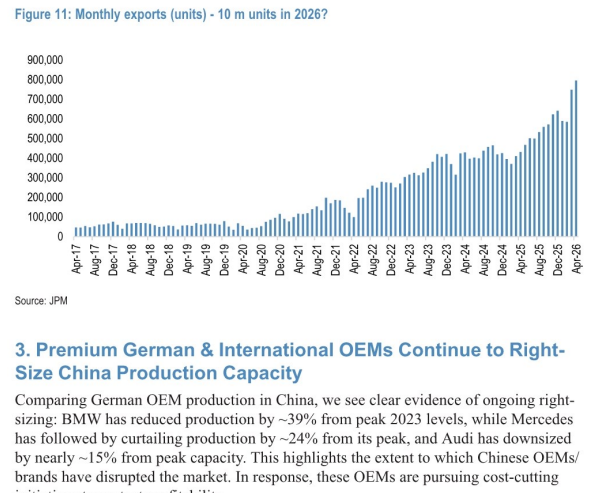
Exhibit 7
Exhibit 8