UBS on Fanuc (6954.T): Maintaining Buy — Upcycle Continues
Summaries are public. PDF access requires an active membership; all members have the same access. Sign in
UBS maintains a Buy rating on Fanuc (6954.T), asserting that the company's upward business cycle remains fully intact. The firm highlights that Fanuc is experiencing robust growth in both orders and revenue, primarily driven by global manufacturing automation trends and escalating AI-related capital expenditure. For fiscal year 2026, UBS projects total revenue of 1.2 trillion yen alongside an operating margin of 30%. The target price is set at 5,500 yen, implying roughly 20% upside potential from current trading levels.
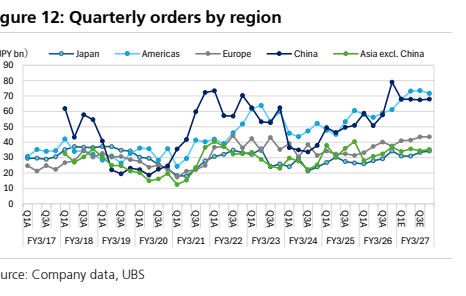
The investment case is anchored by exceptional order momentum. Fanuc has posted year-over-year order growth exceeding 15% for three consecutive quarters, with fiscal year 2026 first-quarter orders surging 18%. AI-driven equipment investment is significantly boosting the robotics division, where revenue is forecasted to grow by 25% in fiscal year 2026. The overall operating margin is expected to expand from 28% in fiscal year 2025 to 30% in fiscal year 2026, aided by operating leverage and stringent cost controls. Additionally, the CNC systems business continues to demonstrate steady performance, benefiting from a recovery in the automotive and machinery sectors.
The target price of 5,500 yen is derived by applying a 30-times price-to-earnings multiple to the projected fiscal year 2027 earnings per share of 180 yen. Key catalysts to monitor include whether order growth can sustain a 15% pace in the second half, and if the robotics segment can achieve a 30% revenue growth target by fiscal year 2027. Downside risks remain limited but include potential global macroeconomic deceleration and adverse foreign exchange fluctuations.
Key exhibits
Exhibit 1
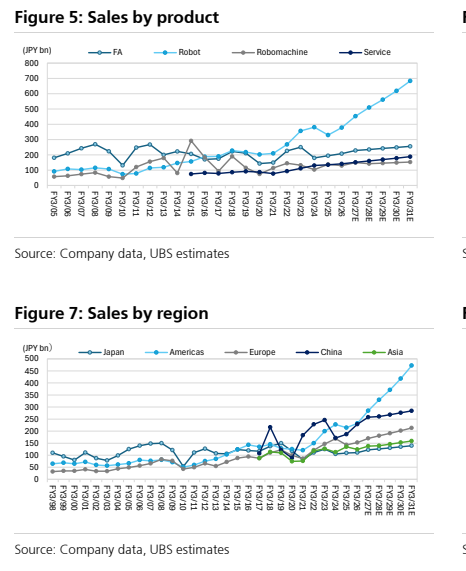
Exhibit 2
Exhibit 3
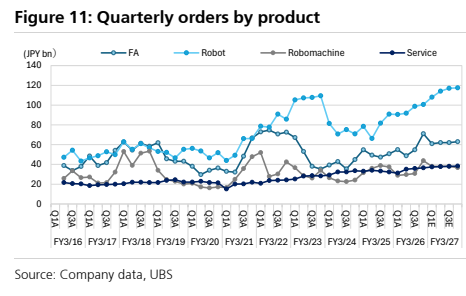
Exhibit 4