Goldman Sachs AMEC (688012): SPE Expansion, High-End Upgrade, AI-Driven Demand; Buy
Summaries are public. PDF access requires an active membership; all members have the same access. Sign in
Goldman Sachs maintains a Buy rating on Advanced Micro-Fabrication Equipment Inc. China (AMEC, 688012), highlighting its strategic transition toward high-end semiconductor processing equipment. The firm expects AMEC to capture a growing share of the etching equipment market at the 5nm node and below, driven by rising demand for advanced manufacturing processes related to artificial intelligence.
Goldman Sachs projects AMEC's revenue will increase by 30% in 2026. The company has successfully introduced etching tools designed for 3nm processes and plans to enter the deposition equipment market by 2027, initially targeting a 5% market share. Gross margin is forecasted to expand from 45% to 48% in 2026, reflecting a higher proportion of premium tool sales. Research and development expenses are expected to remain at 15% of revenue, focused on advancing 3nm and deposition technologies.
Goldman Sachs raised its target price to 180 yuan from 160 yuan, based on a 2027 price-to-earnings multiple of 35 times. The firm views current valuations as attractive given the upward trajectory. Key risks include softer-than-expected downstream demand, intensifying industry competition, and potential disruptions from rapid technological iteration. The 3nm etching tools are slated for mass production in the second half of 2026.
Key exhibits
Exhibit 1
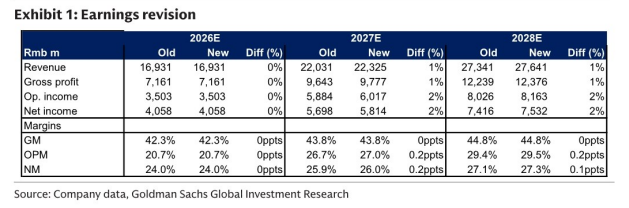
Exhibit 2
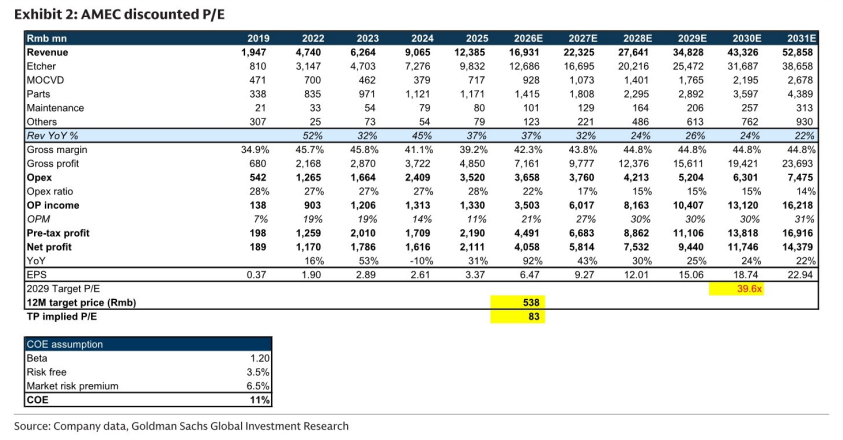
Exhibit 3
