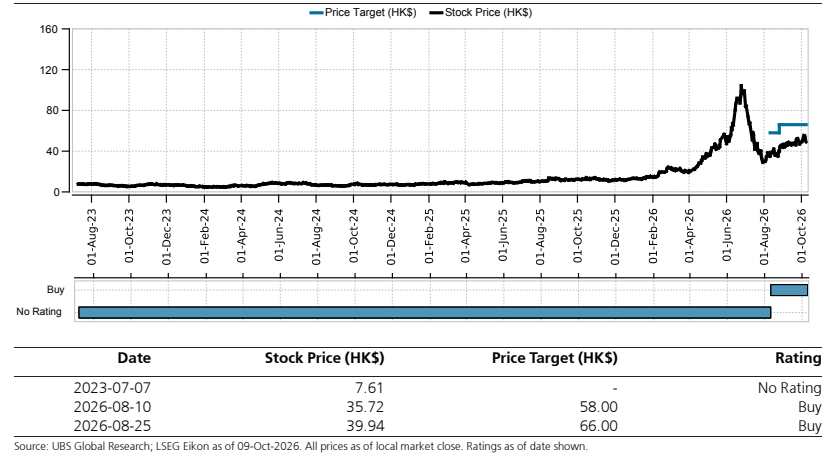
UBS China Copper Clad Laminate Industry: Cycle Update: Raising FR4 ASP; PTFE Demand Pulled Forward
Summaries are public. PDF access requires an active membership; all members have the same access. Sign in
UBS publishes an update on China's copper clad laminate (CCL) industry, arguing the sector is in an upcycle driven by sustained FR4 price increases and strong demand for AI-related high-end materials. The bank raised its FR4 average selling price (ASP) forecasts to Rmb383 by end-2026 and Rmb443 in H1 2027. PTFE, a key material for AI servers, shows demand pull-forward and should deliver meaningful incremental revenue to Shengyi Technology. While the market worries co-packaged optics (CPO) could downgrade CCL content, UBS sees limited near-term risk as AI infrastructure expansion supports high-end CCL demand. Upstream E-glass fabric supply remains tight, with prices expected to rise a further 10-15% in October to above Rmb15. Shengyi Technology holds a first-mover advantage in PTFE and should capture major share in 2027-28; PTFE adoption in NVL576 and Kyber backplanes could add Rmb137mn and Rmb2,635mn of incremental revenue. Kingboard Laminates is lifting loom capacity to 3,733 by end-2026, plus 1,100 more in 2027. Elite Material (EMC) expects M9 to reach a double-digit revenue share in 2027 with yields above 80-90%; M10 is sampling, making end-2026/early-2027 a key watch window. UBS rates Kingboard Laminates (1888.HK) Buy with a target price raised to HK$75, and Shengyi Technology (600183.SS) Buy with a target price raised to Rmb209.
Key exhibits
Exhibit 1
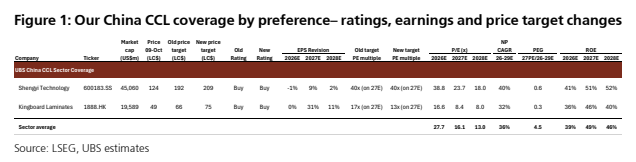
Exhibit 2
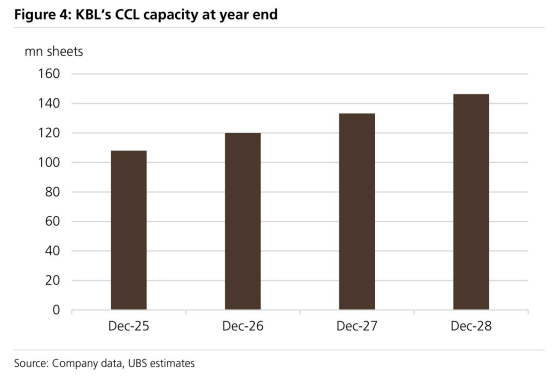
Exhibit 3
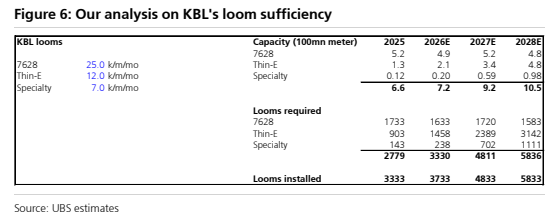
Exhibit 4
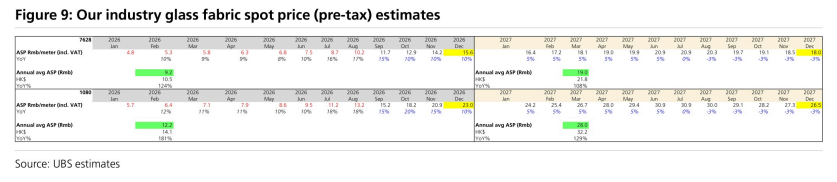
Exhibit 5
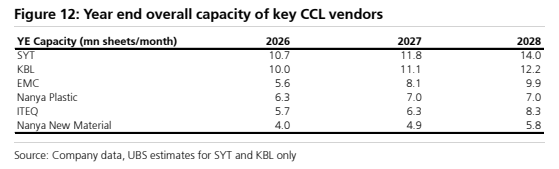
Exhibit 6
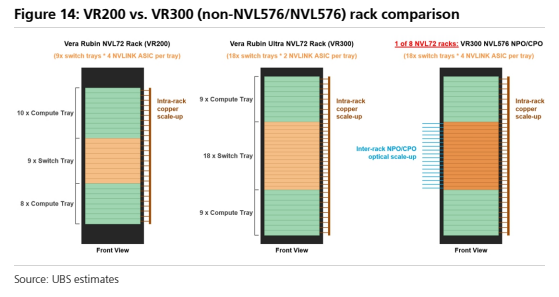
Exhibit 7

Exhibit 8
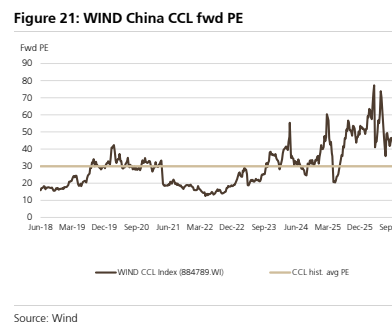
Exhibit 9

Exhibit 10

Exhibit 11

Exhibit 12