Goldman Sachs: China Solar — Tracking Profitability Inflection
Summaries are public. PDF access requires an active membership; all members have the same access. Sign in
Goldman Sachs reports continued upstream pricing weakness across the China solar value chain in June, with average prices declining approximately 5% month-to-date. Film and cell prices led the decline, falling 12% and 11% respectively, driven by an 8% drop in oil prices and a 13% decline in silver prices alongside a 21% surge in inventory.
Cash gross margins deteriorated across upstream segments: cell margins fell 8 percentage points, film 7, polysilicon 4, and glass 3. Conversely, module cash margins improved 2 percentage points due to easing cost pressures.
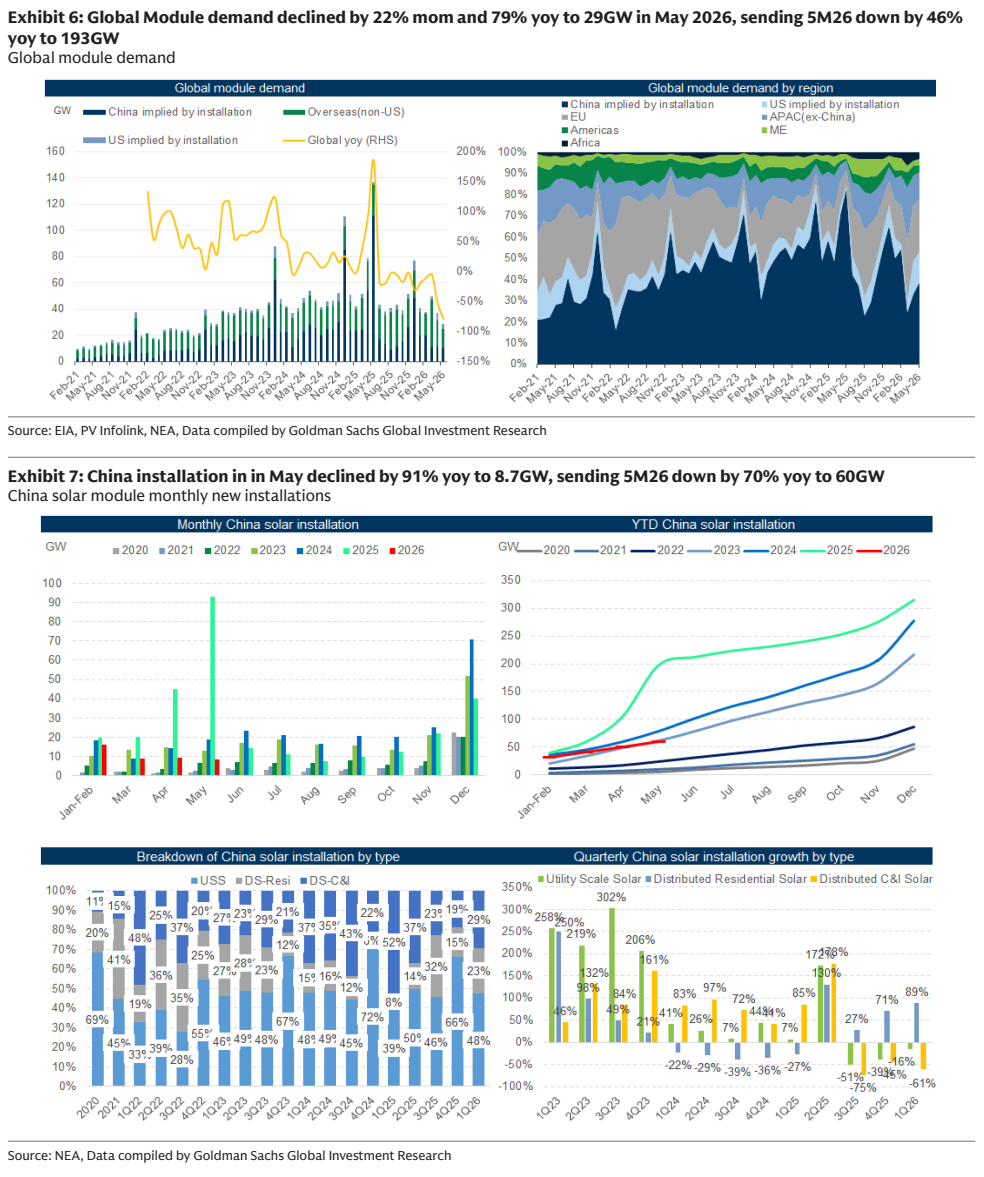
Global module demand declined 79% year-over-year in May to 29 GW, with cumulative 5M26 demand down 46% to 193 GW, trailing full-year expectations of negative 12%. China's installations plunged 91% year-over-year in May to 8.7 GW, while cumulative 5M26 installations fell 70% to 60 GW. Chinese module exports declined 38% year-over-year in May to 15 GW. Demand weakened across the Middle East, Asia-Pacific, EU, and Africa.
Goldman expects pricing softness to persist through the July-August low season due to deteriorating inventory dynamics, softening upstream prices, and Tier 1 manufacturers adopting cheaper metal technologies starting in the third quarter.
Preferred names include Maxwell (Buy, target RMB 278), Hangzhou First (Buy, target RMB 21), and Longi (Buy, target RMB 26). The firm remains cautious on polysilicon and maintains a sell rating on solar glass.
Key exhibits
Exhibit 1
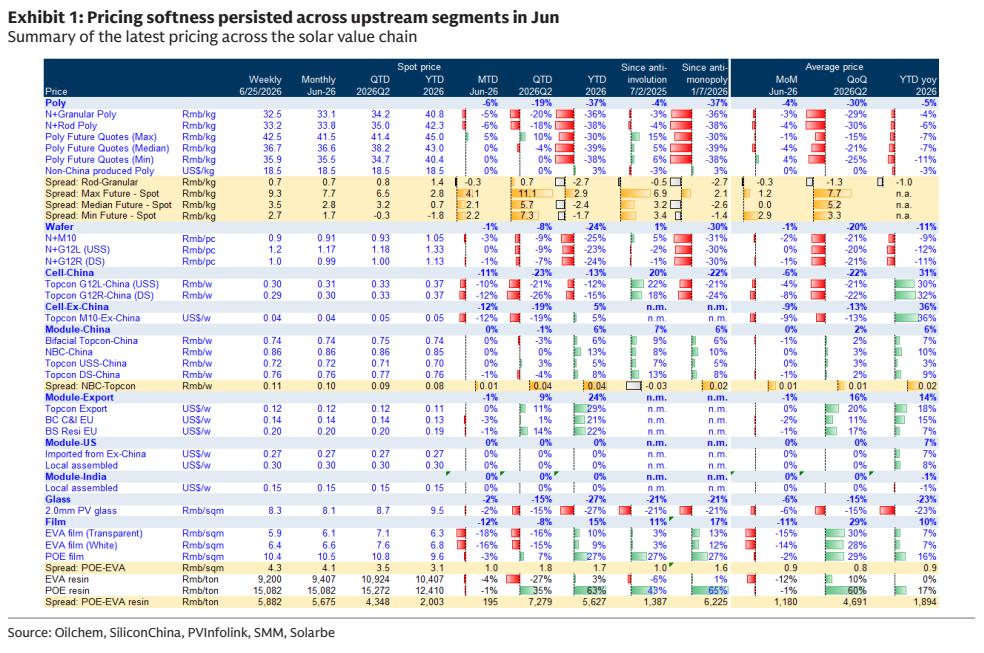
Exhibit 2
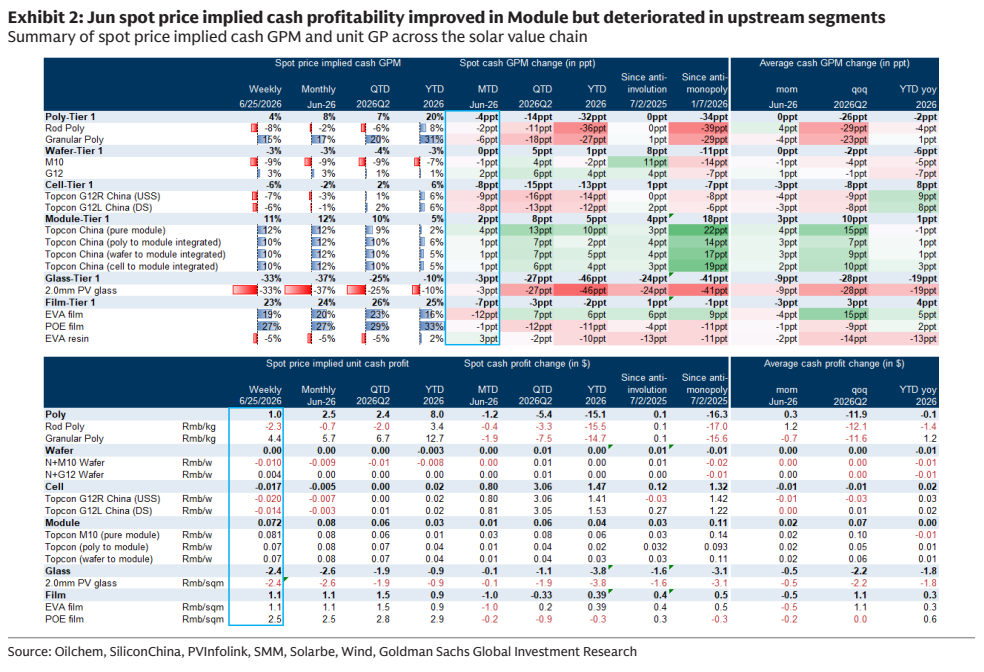
Exhibit 3
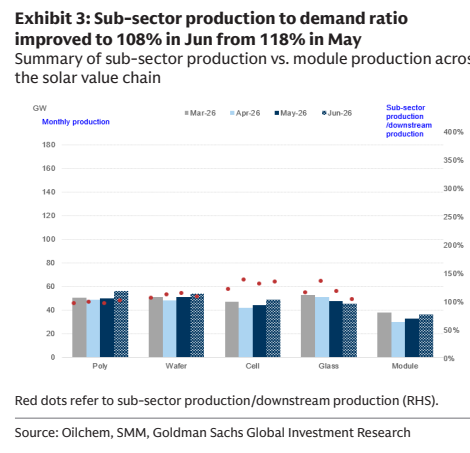
Exhibit 4
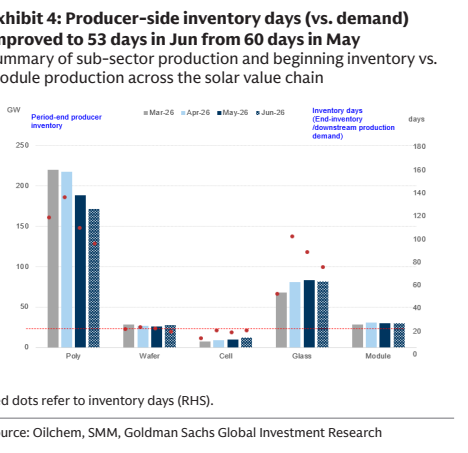
Exhibit 5
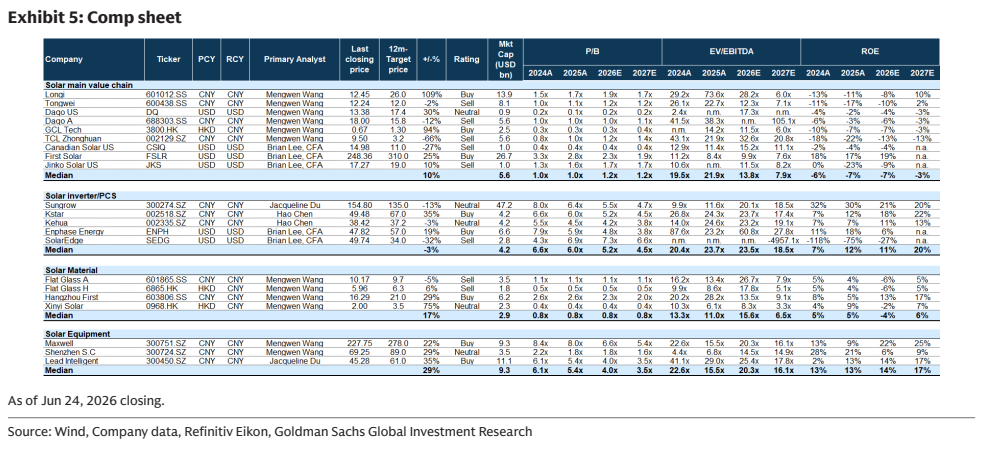
Exhibit 6