JPMorgan Global Factor Performance Summary: September 2026 — AI Re-Rating Meets Surging Long-End Yields
Summaries are public. PDF access requires an active membership; all members have the same access. Sign in
Global factor performance in September 2026 was driven by an AI-related momentum rebound, yet hawkish central banks and a surge in long-end yields left risk appetite cautious. The MSCI ACWI index fell 0.8% over the month. AI and semiconductor shares propelled the price factor to leadership across most regions, but performance lacked breadth, and the quality factor was weak in most markets.
JPMorgan's global Q-Score model delivered a 3.6% long-short return, with the price factor (+7.1%) and earnings factor (+3.1%) contributing strongly, while quality (-1.5%) and valuation (-1.1%) detracted. Regionally, the US price factor surged 13.4%; Europe's price factor gained 5.8% as valuation lagged; Japan's price factor led at +4.0% while quality fell 2.0%.
The report's logic: AI-driven momentum rebounded, hawkish policy pushed long rates higher, dampening risk appetite and hurting quality and valuation factors, producing a narrow, divergent rally.
Looking ahead, with the Quantitative Momentum Indicator (QMI) volatile and lacking breadth, JPMorgan advises caution: maintain a defensive stance in Europe (overweight quality and low volatility, underweight high risk) and keep quality and growth as core US exposures. No individual stock recommendations were provided; the report offers global factor analysis and quantitative strategy guidance.
Key exhibits
Exhibit 1
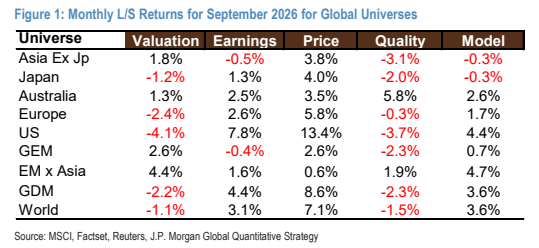
Exhibit 2
Exhibit 3

Exhibit 4

Exhibit 5

Exhibit 6

Exhibit 7

Exhibit 8

Exhibit 9

Exhibit 10
